This article was generated with AI assistance from cited sources and has not been individually reviewed by an editor.
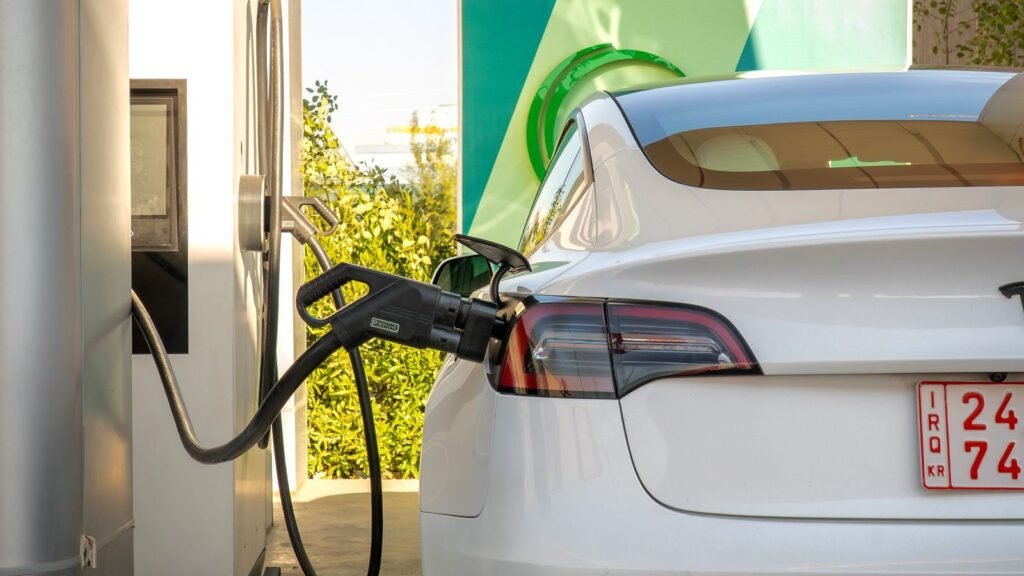
Europe’s electric vehicle charging market is entering a new phase of expansion, driven by regulatory pressure, falling hardware costs, and a steady rise in EV adoption. For homeowners and commercial project owners, the question is no longer whether to install charging infrastructure, but how to choose the right mix of AC and DC systems, software, and financing models.
Demand-side momentum is visible too: electric car registrations made up 23.6% of total new car registrations in 2023, according to preliminary European Environment Agency data.
That shift is feeding directly into charging demand. According to the ICCT’s 2026 EV transition check, the pace of charging infrastructure rollout remains uneven across member states, with some markets already facing utilisation bottlenecks at public fast chargers while others still lag on basic coverage.
The ultra-fast charging segment is where most of the competitive energy is concentrated. According to Fortune Business Insights, the ultra-fast EV charging systems market is projected to grow at a double-digit compound annual rate through 2034.
That growth is attracting new entrants from adjacent industries. Hardware makers, software platforms, and energy retailers are all converging on the same customer: the site owner who wants reliable, high-utilisation charging without owning the entire technology stack.
Charging software is no longer a back-office afterthought. According to Trident Technology, the EV charging software landscape is fragmenting into specialised players covering roaming, payments, load management, and fleet telematics.
For homeowners, the priority is different: simple installation, solar integration, and clear visibility into charging costs. For C&I owners, the priority is uptime, dynamic pricing, and the ability to stack revenue streams such as demand response and grid services.
According to Market Research Future, the global EV charging station market is expected to continue expanding through the end of the decade, with DC fast charging taking a growing share of total installed capacity.
Policy support remains a key variable. The European Environment Agency’s data on electric vehicle uptake shows that countries with consistent purchase incentives and charging mandates are pulling ahead of those relying on market forces alone.
| Segment | Main driver | Main risk |
|---|---|---|
| Home AC charging | Solar self-consumption | Grid connection limits |
| Public AC charging | Destination charging demand | Low utilisation |
| DC fast charging | Fleet and highway demand | Grid capacity and cost |
| Ultra-fast charging | Long-distance and heavy-duty | High capex, competition |
For BessCare readers, the practical implication is straightforward: match charging technology to actual usage patterns, secure grid capacity early, and treat software and service contracts as core infrastructure rather than optional add-ons.